In Africa, Digital Payments Could Unlock Tax Revenue if Data is Protected
Daisy Ogembo / Oct 8, 2026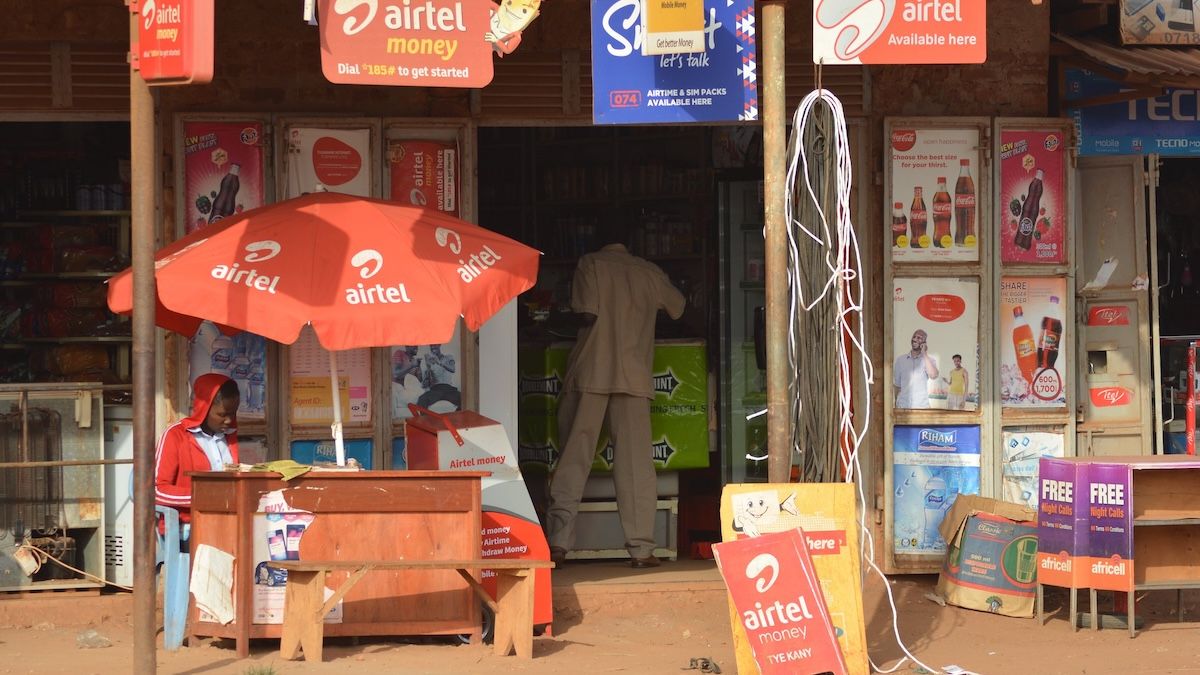
Mobile money agent in Gulu, northern Uganda in 2016 shared by Fiona Graham/WorldRemit on Flickr (CC BY-SA)
Airtel Money, one of Africa's largest mobile money providers, is listing on the London Stock Exchange this month. The company has been valued at $7 billion, in what would be one of London’s largest market debuts in recent years. That valuation is a measure of how central mobile money has become to African economies.
Over the last two decades, mobile money has become part of everyday life in most African economies. According to the World Bank, 40 percent of adults in Sub-Saharan Africa had a mobile money account in 2024, up from 27 percent in 2021. Governments are keen to accelerate this transformation — driven, at least in part, by the promise of economic benefits and financial inclusion — but also to collect taxes.
African countries collect about 16 percent of GDP in tax on average, compared with about 34 percent in OECD countries according to 2023 data. This summer, Ethiopia extended mobile tax payment nationwide through its domestic mobile money platform telebirr, while Uganda, Zambia and Rwanda are also among a long list of countries which now permit payment of some taxes using mobile money.
In high-income countries, income tax is often withdrawn from wages before they are paid; in much of Africa, most people are self-employed or work in small informal businesses, so there is no employer to collect the tax from and little record of what they earn. As economies digitize, automatic or mobile payments can make paying tax quicker and easier, as well as make it harder to avoid the formal tax system. Every mobile money payment leaves a record, and those records enable revenue authorities to compare what a taxpayer declares with what banks, mobile money providers, and other agencies hold.
In Kenya, for instance, tax law allows the revenue authority to demand information from third parties, including mobile network operators. Using data like this across a government can improve compliance and support public service delivery — but it is also reshaping how states exercise authority over their citizens, many of whom may be unaware that their data is being used in this way.
What could go wrong
Australia’s catastrophic Robodebt scheme shows what can go wrong when the rules for data use are unclear. Between 2016 and 2019, the Australian government used averaged annual income data from the tax office to calculate welfare overpayments, as if all people earned the same amount every fortnight. For many people in irregular work, this produced debts that did not exist. The government later acknowledged that around 470,000 debts had been wrongly raised, and the scandal is yet to be fully resolved. The problem was not that tax data was shared. It was that the matching was crude, the burden of proof fell on individuals, and no human checked the results before debts were pursued.
Such disasters are avoidable. Governments already have the tools to build vital safeguards, but too many aren’t using them. As part of my research into digital public infrastructure (DPI) and tax across Africa at the International Centre for Tax and Development at the University of Sussex, my co-author Hannelore Niesten and I have found that some countries, like Kenya and South Africa, have legislation permitting sector-specific data protection codes or guidance for banking and health, for instance — but none for tax. In both countries, the agreements between agencies that govern data exchange have not been published.
Our research identifies three things that governments, tax officials, and regulators can do to harness the potential of tax systems built on DPI without repeating Robodebt’s mistakes. The key is good governance. Understood as an exercise of public authority (and not simply as an administrative function) this is not a constraint on tax capacity but the route to trust, fairness, and compliance.
What could go right
First, governments must set clear guardrails on the use of income and tax data. That means preventing taxpayers from being sanctioned based on tax-related information for reasons unconnected to tax, including welfare (as in Robodebt) or policing without clear legal authority and proper checks.
There are many ways for governments to set limits on the use of tax data, encouraging citizens to participate fully in the tax system without fearing that visibility will lead to unexpected negative repercussions. The best solution will differ depending on political contexts; options include writing purpose limits into legislation, updating outdated Memoranda of Understanding governing data permissions, or simply making data sharing permissions between agencies time-limited.
Next, governments should design DPI-enabled tax systems in consultation with taxpayers, who must in turn be given the tools to understand their obligations. Currently, information about tax obligations can be difficult to find. It may not be available in the right local languages or at the point of use, far from capital cities. In Kenya, for example, ethnic minority communities have historically struggled to access digital ID systems, an important rail of DPI-enabled taxation.
Citizens are understandably reluctant to pay into systems that don’t make obligations clear.
Involving taxpayers from design through to delivery can help make sure everyone understands and can access the system. There are plenty of ways to do it, for instance by testing new systems with small traders, informal workers and women-owned businesses before they are rolled out. This builds the trust that creates long-term buy-in.
But even where governments are unwilling or unable to engage taxpayers in the design process, there are simple ways to help citizens understand their obligations. It’s as easy as making tax information available in the right local languages, in neighbourhoods, at the point of payment.
Clear communication pathways
Finally, adequate recourse must come alongside clear communication. Tax officials sometimes fear that creating new opportunities for taxpayers to challenge decisions will increase the number of disputes; in fact, it can reduce the number of cases that escalate. Tax compliance can be encouraged by lowering the perceived risk of buy-in, and by giving citizens the tools to challenge decisions made about them.
In practice, this means making sure taxpayers have access to clear guidance about who is responsible for correcting an error and how to go about correcting it (e.g. online or at a local tax office). At the same time, regulators should use the powers they already have to act when tax data use is changed without authorisation.
Most importantly, there must be a human in the loop before automated decisions lead to enforcement action, so that ordinary taxpayers are not punished for errors made by automated systems. The legal tools for this already exist. South Africa’s data protection law, for instance, generally bars decisions based solely on automated processing that have legal consequences for a person. It makes an exception where a law or a code of conduct sets out safeguards. The person must be able to respond and must be told enough about how the decision was reached to do so. No such code exists for tax. Issuing one would give taxpayers these protections and settle how the rule applies when automated systems are used to select taxpayers for scrutiny.
As companies like Airtel make cashless payments the norm, the secure exchange of tax data can help realize the spectacular promises of DPI for domestic revenue mobilization and economic formalization throughout Africa. But without embedding trust and accountability by design, those systems can alienate those expected to pay in — in turn, damaging governments’ very ability to levy tax.
Authors